Until May 1997, Social Security benefits were paid on the 3rd of each month. That was true whether you were receiving retirement benefits or Social Security disability benefits (SSDI). Now, the date that your disability pay arrives depends on the type of benefit you receive and your birth date.
The Social Security Administration (SSA) processes payments for several different programs. A disabled person may receive SSDI, Supplemental Security Income (SSI) or both. SSDI benefits are based on your work history, just like your Social Security retirement benefits. SSI is a needs-based program that is administered by the SSA but is funded separately.
SSDI and SSI recipients will see a 3.6% Cost-of-Living Adjustment (COLA) in 2027, the largest increase since 2023. According to SSA’s 2027 fact sheet, the average monthly benefit for disabled workers will rise by about $59, from $1,642 to $1,701. SSDI recipients see the increase starting with their January 2027 payment. SSI recipients see it a little sooner, in the payment that arrives December 31st, 2026.
Here’s what you can expect if you are receiving SSDI, SSI or both.
SSDI Disability Payment Schedule
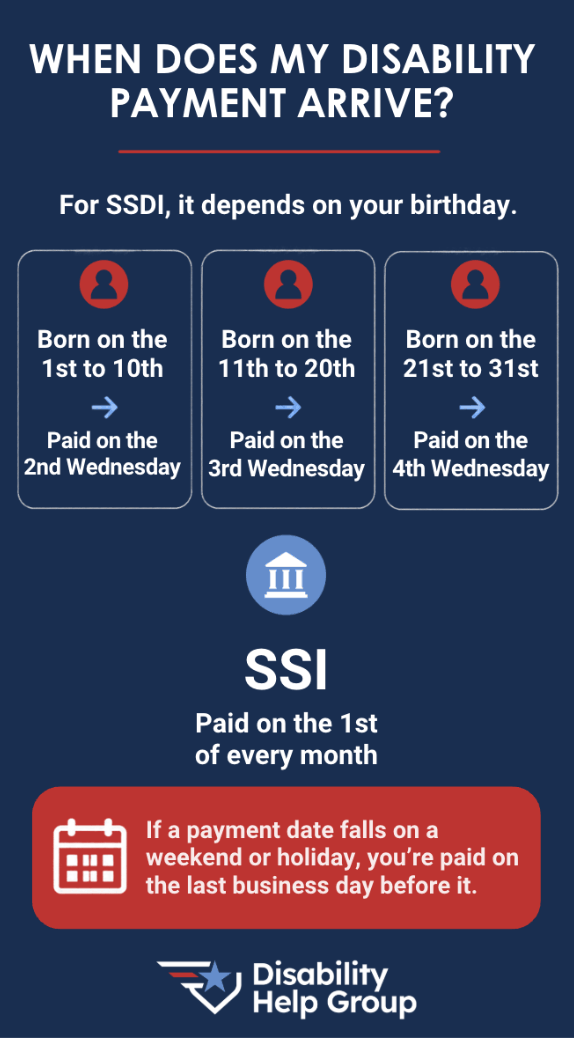
If you started receiving SSDI benefits after April 1997, your birthday will determine the date you receive your payment. Under the current Social Security disability payment schedule, if your birthday falls between:
1st-10th of a month, SSDI checks or direct deposit will arrive on the second Wednesday of every month.
11th-20th of a month, SSDI checks or direct deposit will arrive on the third Wednesday of every month.
21st-31st of a month, SSDI checks or direct deposit will arrive on the fourth Wednesday of every month.
If you received benefits before 1997, your SSDI payment date will be on the third day of the month.
If you received benefits before May 1997, your SSDI payment date will be on the third day of the month.
While SSDI payment dates are spread throughout the month based on your birth date, all SSI payments are made on the first day of the month. If the first falls on a weekend or federal holiday, your SSI payment is issued on the last business day before the holiday.
January payment: December 31st, 2026 (New Year’s Day falls on a Friday)
February 1st, March 1st, April 1st
May payment: April 30th (May 1st is a Saturday)
June 1st, July 1st
August payment: July 30th (August 1st is a Sunday)
September 1st, October 1st, November 1st, December 1st
January 2028 payment: December 30th, 2027 (New Year’s Day 2028 falls on a Saturday, so the holiday is observed Friday, December 31st)
That means SSI recipients will get two payments in April, July and December 2027, and none in January, May or August. The money isn’t extra or missing. It just arrives early. If you budget month to month, it’s worth marking those dates.
How Does the SSA Treat Weekends and Holidays?
Since most SSDI payment dates fall on Wednesdays, that payment schedule is generally not disrupted by federal holidays, and those dates obviously never fall on Saturday or Sunday. That’s not true for SSI payments, which are scheduled for the first of the month, nor for those SSDI payments that are made on the third day of the month.
When the first or third day of the month falls on a Saturday, Sunday, or holiday, those payments are made on the last regular business day before the scheduled payment date.
For people paid on the 3rd, the January 2027 payment arrives on December 31st, 2026, because January 3rd is a Sunday and January 1st is a holiday. In 2027, payments normally due on the 3rd will also come early in April (April 2nd), July (July 2nd) and October (October 1st).
SSDI and SSI Combined Payments Schedule
If you receive SSDI and SSI payments together, you will receive your SSI payment on the first day of the month and your SSDI payment on the third of the month.
The combined schedule remains the same, and adjustments for holidays and weekends are automatic. The 2027 dates for payments on the 3rd are: December 31st, 2026 (for January), February 3rd, March 3, April 2nd, May 3rd, June 3rd, July 2nd, August 3rd, September 3rd, October 1st, November 3rd and December 3rd.
How Long Does it Take to Receive SSDI Payments?
How long it takes to receive your monthly benefits and back pay after you’ve been approved for SSDI benefits varies. Most recipients start getting benefits one to two months after approval, and back pay often arrives in that same time frame. It can take longer if SSA has to sort out other benefits first, such as workers’ compensation or a pending SSI claim.
If you apply for SSDI immediately upon becoming disabled and your claim is approved quickly, you may have to wait a little longer. That’s because there is a five month waiting period between onset of your disability and the time you become eligible for benefits. So, for example, if you become disabled in January and are approved for benefits in April, you’ll have to wait a few months for your benefits to kick in.
You won’t have to guess at this, though. Your SSDI award letter will include a “date of entitlement,” which is the first month you will be eligible to receive benefits. If you don’t start receiving benefits on schedule, you should contact the SSA for help.
Direct Deposit is probably the safest way to receive your disability payments since they cannot be lost or stolen if deposited directly into your bank account.
The Direct Express Card program, which loads your benefits onto a prepaid debit card. It’s a good option if you don’t have a bank account.
If you still receive a paper check, switch as soon as possible through your my Social Security account or your bank. Paper checks are only available in rare cases, through a waiver from the Treasury Department.
Tax on Social Security Benefits
You may have to pay taxes on SSDI depending on your income level. SSDI income, like Social Security retirement income, is taxable only if the total of your other income plus 50% of your Social Security income exceeds:
$25,000 if your tax filing status is single, head of household, qualifying surviving spouse, or married filing separately and have lived apart from your spouse for the full year
$32,000 for married couples filing jointly
$0 for married couples filing separately who lived together at any point during the tax year
Above those amounts, up to 50% of your benefits can be taxable. If your combined income goes over $34,000 (single) or $44,000 (married filing jointly), up to 85% of your benefits can be taxable.
SSI income is not taxable.
Social Security doesn’t automatically withhold taxes, but does offer voluntary tax withholding from your benefit. You can choose this option by completing Form W-4V. There are specific percentages to choose from. You can obtain the form from Social Security, request it from the IRS, or ask your representative for a copy.
Generally, you would receive a refund when filing taxes the following year if you opted to voluntarily have taxes withheld and you overpaid.
These thresholds don’t adjust for inflation. They’ve been the same for decades, which is why more people owe some tax on their benefits over time. If you’re getting a large back paycheck, read SSDI Back Pay and Taxes: What You’ll Actually Owe.
Call Now for a Free Case Review, (800) 800-3332
Make sure you start your claim the right way and apply for all the benefits you deserve. Contact us here to receive a FREE consultation.
Frequently Asked Questions
When will I receive my SSDI payment in 2027?
Payment depends on your birth date if you started receiving benefits after April 1997:
1st–10th → 2nd Wednesday of the month
11th–20th → 3rd Wednesday of the month
21st–31st → 4th Wednesday of the month
If you started receiving benefits before May 1997, your payment is on the 3rd of the month.
What is the 2027 SSDI Cost-of-Living Adjustment (COLA)?
SSDI and SSI benefits increase by 3.6% in 2027. SSA estimates the average disabled worker’s benefit will rise from $1,642 to $1,701 a month. SSDI recipients see it in their January 2027 payment, and SSI recipients see it in the payment arriving December 31st, 2026.
How are payments affected by holidays or weekends?
If a scheduled payment date falls on a Saturday, Sunday, or federal holiday, SSA issues the payment on the last business day before the holiday. This may result in two payments in one month or a slight delay in the following month.
Can I receive both SSI and SSDI at the same time?
Yes. SSI is paid on the first of the month, and SSDI is paid according to your birth date (or the 3rd of the month if you started before May 1997). Payments are separate but coordinated by SSA.
How can I make sure I receive my payments safely?
The safest methods are:
Direct Deposit: money goes directly into your bank account
Direct Express Card: a prepaid, swipeable card
Paper checks are being phased out for all federal benefits, with only rare exceptions, so make sure SSA has your direct deposit or Direct Express information.
What is a Residual Functional Capacity Form? Residual functional capacity (RFC) forms can help support your Social Security disability claim. RFC forms explain how your symptoms impact your ability to perform work activities. Social Security does not award benefits on your diagnosis alone. Therefore, you must show that your medical conditions keep you from being able to work.
Disability Help Group provides a Residual Functional Capacity form to all of our clients. You can download a copy HERE. It is a 20-question medical source statement covering sitting, standing, and walking, lifting and carrying, use of the arms and hands, and the symptoms that interfere with staying on task. The rest of this page explains what each part of it is for and how Social Security will read it.
What is my residual functional capacity?
Residual functional capacity (RFC) is defined as the most you can do despite your medical impairments. A Residual Functional Capacity form can include both mental and physical limitations. Your Residual Functional Capacity is very important. First, Social Security looks at whether your condition meets one of the medical listings. Most conditions won’t be severe enough to meet one of the medical listings. Therefore, Social Security needs to look at your residual functional capacity.
How does Social Security use Residual Functional Capacity forms?
A Residual Functional Capacity form helps Social Security understand how your conditions impact your ability to perform activities. The forms are used by SSA’s Disability Determination Services (DDS) office to process your claim. A Social Security medical consultant reviews your medical records. They complete an RFC form based on the information they have. Additionally, they will provide an explanation for their findings. Next, Social Security looks at whether or not your Residual Functional Capacity form allows them to approve your claim.
That consultant has never met you. They are working from whatever is in your file. This is the gap an RFC form from your own doctor is meant to close.
Why your doctor’s opinion no longer wins on its own
This is the part most articles about Residual Functional Capacity forms still get wrong, and it changes how the form should be filled out.
Social Security used to give a treating doctor’s opinion controlling weight in most cases. That rule is gone. For any claim filed on or after March 27, 2017, Social Security says it will not defer to or give any specific evidentiary weight, including controlling weight, to any medical opinion, including one from your own doctor.
Instead, every opinion is judged on how persuasive it is.
Two factors matter most, and the adjudicator has to explain both:
Supportability. Did the doctor explain the reasoning and point to objective findings? An opinion grounded in imaging, clinical testing, and examination findings is persuasive. A conclusion with nothing behind it is not.
Consistency. Does the opinion match the rest of the record? If the form says you cannot sit more than two hours but your treatment notes never mention back pain, Social Security will notice.
Three other factors get considered but carry less weight: the doctor’s relationship with you, their specialization, and other relevant factors. Your treating doctor can still be the most persuasive source in the file. It just has to be earned now rather than assumed.
Why the checkboxes alone are not enough
Courts have been skeptical of bare checkbox forms for decades, and under the persuasiveness standard, that skepticism has teeth. A form with every box ticked and every explanation left blank is exactly the kind of opinion an adjudicator can find unsupported and set aside.
Our form is built to prevent that. It has open explanation fields after the assistive device question, the standing and walking limits, the hand limitation questions, and a full open-ended question at the end asking for anything else relevant to whether you can work on a regular and consistent basis. There is also an onset date section asking the doctor to state what the opinion is based on, with boxes for direct observation and treatment, clinical testing, imaging and labs, physical examination, functional testing, and historical records.
Those fields are the supportability half of the test. If your doctor fills in the boxes and skips the writing, the form is worth much less than it looks.
Physical Residual Functional Capacity forms
A physical Residual Functional Capacity form includes questions about your ability to do things like:
How long you can sit, stand or walk at one time or in an 8 hour work day
How much weight you can lift or carry
If you need an assistive device such as a cane, walker, wheelchair or crutches
Using your arms and hands for activities such as reaching, pushing, pulling, gripping or grasping objects
If pain, fatigue, other symptoms or side effects from medications cause limitations with concentration, persistence or pace
The instructions on our form tell the doctor to answer these questions against a specific standard: an eight-hour day, five days a week, with a fifteen-minute break in the morning, fifteen in the afternoon, and thirty minutes for lunch. That is what Social Security means by competitive work. The instructions also tell the doctor to disregard your age, education, and past work, because those get considered separately at a later step.
What the numbers on the form actually decide
The sitting, standing, and weight brackets are not arbitrary. Social Security sorts work into exertional levels, and your answers place you in one of them.
Sedentary work generally means lifting no more than 10 pounds, sitting for about six hours of an eight-hour day, and standing or walking about two hours. Light work generally means lifting up to 20 pounds occasionally and 10 pounds frequently, with a good deal more standing and walking. Medium work generally means lifting up to 50 pounds occasionally and 25 pounds frequently.
This is why the difference between checking “2 hours out of an 8-hour workday” and “3-4 hours” can decide a case. It is also why the form asks separately about lifting for one-third of the day and lifting for two-thirds of the day. Occasionally and frequently are terms of art, and Social Security uses them to sort you.
Mental Residual Functional Capacity Forms
A mental Residual Functional Capacity form includes questions about your ability to do things like:
Your ability to understand, remember or carry out instructions or interact with others such as supervisors, co-workers or the general public
Your ability to maintain attention and concentration
If your symptoms interfere with your ability to show up to work, arrive on time or have to leave early
Our physical form also captures this ground. It asks whether medication side effects, pain, fatigue, dizziness, or shortness of breath affect your ability to function, and then asks the doctor to rate how serious those symptoms are on a three-point scale. Mild means you generally perform well with short or infrequent interference. Moderate means interference with concentration, persistence, or pace up to a third of eight hours. Marked means interference up to two-thirds.
Pay attention to that scale. At a hearing, a vocational expert will usually testify that a worker who is off task more than about ten to fifteen percent of the day, or who misses more than a couple of days a month, cannot hold competitive employment. A “moderate” or “marked” rating on that question is often the single most valuable answer on the form.
Residual Functional Capacity forms for your doctors
Your treating doctors may also complete a Residual Functional Capacity form. Having your doctor complete an RFC form can be very helpful. After all, they should know more about your health than anyone else. An RFC form should be very detailed. It should include all your medical symptoms and conditions. It should also include all of your treatment and any side effects from medications.
A few practical notes. Our form asks the doctor to consider how well you function while taking your medications, not how you would function without treatment, because that is how Social Security evaluates it. If a nurse practitioner, physician assistant, or therapist completes the form, a doctor still needs to review and sign it for it to carry appropriate weight. And the last question asks whether Social Security may contact the office about the opinion, which is worth saying yes to.
The importance of residual functional capacity forms
Social Security considers more than just your diagnosis. They need to understand how your conditions affect your functioning. Therefore, even if you think your medical evidence is strong, Residual Functional Capacity forms can help strengthen your case. Many times, medical records do not clearly translate how your symptoms impact your functioning.
Specifically, your doctor’s Residual Functional Capacity form can:
Provide your treating doctor’s opinion about how significantly your conditions impact your functioning
Provide your doctor’s opinion in the specific way Social Security evaluates functioning
Can help win your disability case especially if you are appearing before an Administrative Law Judge
Treatment notes are written to treat you, not to answer Social Security’s questions. A chart that says “patient reports ongoing low back pain, continue current regimen” tells an adjudicator almost nothing about how long you can sit. The form asks the questions your records were never written to answer.
How a residual functional capacity form can help win your case
Social Security considers your age, education, and work background when evaluating your claim. If you are under the age of 50, you must show that you cannot work at all. Social Security will consider other types of work, not just the work you have done in the past. A Residual Functional Capacity form can help explain why you may not be able to work on a full-time basis.
Example 1: Residual functional capacity forms
For example, say you are under the age of 50 and worked before as a cashier. You have a back injury that interferes with your ability to do this type of work. You also have side effects from your medications that make you drowsy. In a Residual Functional Capacity form, your doctor states that you cannot sit for more than 4 hours or stand or walk for more than 2 hours in a workday. Your doctor also states that you have problems with attention and focus due to your medications. These limitations help support your disability claim because it shows that you could not work a full 8-hour day.
Residual functional capacity forms and the Grid Rules
Social Security recognizes that it may be harder for older individuals to learn new work. Therefore, there are more favorable rules for people 50 or older. These rules are known as the Grid Rules. They are even more favorable if you are 55 or older. Essentially, the Grid Rules consider your age, education and work background. If Social Security finds that you can’t go back to work you have done in the past five years, you might be disabled.
That five year figure is new. Social Security used to look back 15 years at your past relevant work. Under a final rule effective June 8, 2024, applied to claims pending or filed on or after June 22, 2024, the look-back period is five years. Work that started and stopped in fewer than 30 calendar days does not count at all. The rule is at 20 CFR § 404.1560, and SSR 24-2p explains how Social Security applies it.
This change helps claimants, and it helps most at the grid rules. A shorter look-back gives Social Security a smaller pool of jobs to say you can return to, and fewer chances to find transferable skills from work you did a decade ago. If your claim was decided under the old 15 year rule and the five year rule would have changed the outcome, that is worth raising with a representative.
Example 2: Residual functional capacity forms and the Grid Rules
For example, Ellen, a 53 year old woman previously worked as a cashier. She filed for disability because she developed osteoarthritis in her knees. She can no longer stand or walk for long periods of time. In an RFC form, her doctor stated that she could not stand or walk for more than 2 hours a day but can sit for at least 6 hours a day. Her doctor also reported that she needed a cane when walking. She cannot work as a cashier. Even though she can do seated work, the Grid Rules allowed Social Security to approve her case.
Example 3: Residual functional capacity forms and the Grid Rules
In another example, Adam, a 57-year-old, previously worked as a janitor. His job required him to lift and carry over 50 pounds occasionally. Adam injured his back and can no longer perform his job duties. In an RFC form, Adam’s doctor reported that he could not lift more than 20 pounds. He also reported that Adam could only stand or walk for 4 hours a day. Even though Adam could do other work, the Grid Rules allowed Social Security to approve his case.
How to get the form filled out
Bring it to the doctor who treats the condition you are claiming, not whoever you can get an appointment with soonest. Specialization is one of the persuasive factors, and an orthopedist’s opinion on your knees carries more weight than a walk-in clinic’s.
Ask them to fill in the written explanations, not just the boxes. Say why: Social Security weighs whether the opinion is supported by objective findings and an explanation.
Ask them to complete the onset date section and sign it. An opinion that describes limitations without saying when they began leaves Social Security free to pick a later date, which affects your back pay.
Read it before it goes in. If the form says you can lift 25 pounds and you told the examiner you cannot lift a gallon of milk, that inconsistency will hurt you more than the form helps.
Some offices charge for completing forms, and some will not complete them at all. If your doctor declines, tell your representative early rather than at the hearing.
Frequently Asked Questions About RFC Forms
Do I have to submit an RFC form?
No. Social Security will assess your residual functional capacity whether or not you submit anything. The question is whether that assessment gets made by a consultant who has only read your file, or with input from the doctor who treats you.
Does Social Security have to accept what my doctor writes?
No. Since March 27, 2017, no medical opinion gets controlling weight, including your treating doctor’s. Under 20 CFR § 404.1520c, opinions are weighed on persuasiveness, and supportability and consistency are the two factors that matter most.
Is it too late to submit one if I already got denied?
Usually not. RFC forms often do the most good on appeal, particularly before an Administrative Law Judge, where the limitations in the form can be put to a vocational expert directly. Deadlines apply at each appeal level, so move quickly.
What if my doctor will not fill it out?
Some will not, as a matter of office policy. Options include asking a different treating provider, asking whether a nurse practitioner or physician assistant can complete it for a doctor to review and sign, or building the case on treatment records and testimony instead. Tell your representative early.
Does Social Security look at 15 years of my work history?
Not anymore. As of June 2024, the look-back period for past relevant work is five years, and work lasting fewer than 30 calendar days does not count.
Why does the form ask about lifting for one third and two thirds of the day?
Because Social Security defines occasionally as up to one third of the workday and frequently as up to two thirds, and the exertional levels are built on those definitions. The two answers together decide whether you are limited to sedentary, light, or medium work.
What is the most important question on the form?
For many claims it is the one asking how seriously your symptoms interfere with concentration, persistence, and pace, and the open-ended question at the end. Vocational experts testify that being off task beyond a small percentage of the day rules out competitive work, and that testimony is what wins hearings.
Disability Help Group, Call Now for a Free Case Review
Make sure you start your claim the right way and apply for all the benefits you deserve. If you would like help getting an RFC form in front of the right doctor and into your file correctly, contact us for a free consultation HERE.
For most people, Social Security disability (SSD) benefits do not change when the recipient reaches full retirement age. Instead, an invisible shift takes place. When a disability recipient reaches full retirement age, the Social Security Administration (SSA) moves them from disability benefits to retirement benefits. For most people, the amount of the monthly benefit won’t change. In fact, you likely won’t notice any difference at all.
Why is My Retirement Benefit the Same as My Social Security Disability Benefit?
Social Security benefits, whether retirement benefits or SSD benefits, are based on your Social Security work history. If you have accrued sufficient Social Security work credits to qualify for SSD, your SSD benefit is the same amount as you would receive if you retired at full retirement age. Of course, that amount changes from year to year with the cost-of-living adjustment (COLA), but those increases are the same whether you are receiving retirement benefits or SSD.
Since the benefit amount for SSD and for retiring at full retirement age is identical, most people don’t see any change in their checks when they retire. However, there are a few limited circumstances in which your benefits may change.
Why Might My Social Security Benefit Change When I Reach Retirement Age?
In some limited circumstances, you will see a change in the amount of your Social Security benefit when you switch from SSD benefits to retirement benefits. The good news is that if that happens, the change is typically in your favor. This generally happens when your SSD benefits have been reduced.
One of the most common examples is a person who qualifies for both SSD and workers’ compensation disability pay. You can collect both benefits at the same time. However, the SSA has a rule that says the combined benefit cannot be more than 80% of your pre-disability earnings.
Depending on the state, workers’ compensation disability benefits typically replace 50% to 66.67% of your pre-disability earnings. For most SSD recipients, that means SSD benefits will be cut to keep the total at 80% of prior earnings. But that rule doesn’t apply to retirement benefits. So, when your SSD benefit switches to a retirement benefit, you’ll begin receiving the full amount. A similar reduction can occur with certain other types of disability benefits.
When Does SSD Switch to Social Security Retirement Benefits?
Your benefits shift from SSD to retirement benefits when you reach full retirement age. Full retirement age is different depending on the year you were born. However, under current law everyone born in 1960 or later reaches full retirement age at 67. That means that as of July of 2026, only a very small percentage of workers and Social Security disability recipients have a different full retirement date. Those born in September through December of 1959 will reach full retirement age at 66 years and 10 months of age.
It’s important to note, though, that these milestones could change. In the past several years, there have been multiple proposals to raise the Social Security retirement age.
What If I’m Also Receiving SSI?
SSI is a need-based program. Since your income from the SSA won’t change, your SSI benefit should not be affected. While different types of income are treated differently for SSI eligibility purposes and determining the amount of SSI benefits you receive, Social Security disability and Social Security retirement benefits both fall into the same category–unearned income–and so are treated the same.
What if My Spouse is Collecting Social Security on My Record?
If your spouse has been collecting Social Security benefits based on your record while you were collecting SSDI, they will continue to receive benefits after the SSA shifts you to retirement benefits. Their benefits will typically also be unchanged. However, it’s important to be aware that if they took those benefits early, their benefits will remain reduced even though you have reached full retirement age.
What Happens to Medicare When I Reach Retirement Age?
If you’re reaching full retirement age, you should already be on Medicare. SSD recipients are typically eligible for Medicare coverage after two years on disability. But anyone who has reached full retirement age and is a US citizen or permanent legal resident should already be eligible for Medicare–that kicks in at age 65. If you don’t already have Medicare coverage, you can apply. However, you will likely need to wait for the next general enrollment period (in the first quarter of the year), and may pay higher premiums because you are applying late.
Working on SSD v. Social Security Retirement
Some people who are receiving SSD work, though earnings are strictly limited. In 2026, any month in which you earn more than $1,210 counts as a trial work period–rack up just nine of those across five years and the SSA will start phasing you off of SSD.
Before full retirement age, there’s a limit of sorts on earnings for Social Security retirement benefit recipients, too. Though there’s no actual cap on earnings, anything over a set amount per year ($24,480 in 2026) triggers a reduction in benefits–you lose $1 for every $2 you earn.
That all ends at full retirement age. There’s no earnings cap and no offset. If you choose to work in retirement and you’re past full retirement age, you keep all your earnings. However, depending on the amount of your earnings, you may have to pay income tax on part of your Social Security income.
Navigating Social Security Can Be Complicated
As you can see, there are many variables impacting your Social Security disability eligibility, the amount of your benefits, and how those benefits impact or are impacted by other benefits. If you’re planning to apply for Social Security disability or have applied for SSD and been denied, an experienced disability benefits advocate can be your best resource. To learn more about what Disability Help Group can do for you, call us today at 800-800-3332 or fill out our contact form HERE for a FREE case evaluation.
FAQ’s
Does my SSD benefit amount go down when I switch to retirement benefits? No, and in some cases it goes up. SSD and full retirement age benefits are calculated from the same work history, so the amount is typically identical. The exception is if you’re also collecting workers’ comp or another disability benefit that triggered a reduction under the 80% rule, that offset doesn’t apply to retirement benefits, so your check can actually increase.
Will this affect my SSI or my spouse’s benefits? Your SSI shouldn’t change, since SSD and retirement income are both treated as unearned income for SSI purposes. If your spouse collects on your record, their benefit typically stays the same too, though if they claimed early, their reduction stays in place even after you hit full retirement age.
Do I need to do anything to make this switch happen? No. The SSA moves you from SSD to retirement benefits automatically once you hit full retirement age (67 for anyone born in 1960 or later). There’s no application or paperwork on your end.
“Social Security disability” technically refers to the SSDI (or SSD) program. However, people often interchangeably use the term to refer to SSD and Supplemental Security Income (SSI). While both programs are administered by the Social Security Administration (SSA), they are very different. SSD is funded by FICA contributions deducted from your paycheck. SSI, on the other hand, is a need-based program funded by the Treasury.
To qualify for SSDI benefits, you must have earned a certain number of work credits over your career and a smaller number in the 10 years before you became disabled. In 2026, you earn one work credit for every $1,890 in covered earnings, up to four credits per year ($7,560 total). How many credits you need depends on your age when you became disabled, someone disabled at 27 needs far fewer credits than someone disabled at 55.
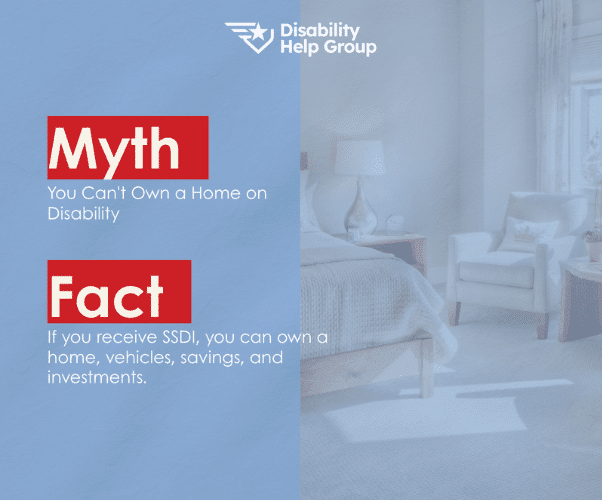
SSDI works like an insurance program, so your assets don’t disqualify you. You can have a house, a car, a retirement account, savings, investments, none of it counts against you. There’s also no limit on income from sources other than work. The one thing that matters is how much you earn from working. If your earnings from a job or self-employment go above a set monthly threshold, the SSA presumes you’re capable of substantial work and won’t consider you disabled for benefit purposes.
That threshold is called Substantial Gainful Activity, or SGA. For 2026, the SGA limits are:
$1,690 per month for non-blind individuals (up from $1,620 in 2025)
$2,830 per month for statutorily blind individuals (up from $2,700 in 2025)
These figures are gross earnings, before taxes, and they’re adjusted most years to keep pace with wage growth.
Trial Work Period: Testing The Waters Without Losing Benefits
If you’re already receiving SSDI and want to try going back to work, you don’t automatically lose your benefit the moment you cross the SGA line. The SSA gives you a Trial Work Period (TWP), up to nine months (they don’t have to be consecutive) within a rolling 60-month window where you can earn above SGA and still collect your full SSDI check. In 2026, any month you earn more than $1,210 counts as a TWP month. Once you’ve used all nine, your earnings going forward are measured against the standard SGA amount, and if you consistently earn above it, your benefits stop. There’s also a 36-month Extended Period of Eligibility after the TWP that offers additional protection, so a single good month at work won’t necessarily end your case.
What Can You Own on Social Security Disability: Unearned Income
Unearned income is money that is earned outside of a job. Under SSDI, you can receive income from other sources and still qualify to receive benefits.
Examples of unearned income include:
Income from retirement accounts, dividends or stocks
Rental income, unless you are in the business of operating rental properties
Gifts from friends or family
Proceeds from the sale of property
Alimony or child support
Contributions to or growth in an ABLE account (see below)
What Can You Own on SSI?
SSI pays monthly benefits for low-income disabled adults and children and low-income senior citizens. Because SSI is a need-based program, the SSA will consider both your income and assets in determining eligibility. To qualify, you must:
Have less than $2,000 in countable assets (or $3,000 for a couple)
Worth noting: that $2,000/$3,000 resource limit hasn’t been raised in decades. It isn’t tied to inflation, so it buys a lot less than it used to, and a modest emergency fund or an old life insurance policy can push someone over the line without them realizing it.
What Counts Towards The SSI Asset Limit?
Social Security calls assets “resources.” Resources include money, but also other types of property that have value. Resources include:
Cash or any money in a checking or savings account
Life insurance policies, stocks, bonds or retirement accounts
A second car, boat, or other vehicle beyond your primary one
Any other property that could be converted to cash and used for food or shelter
What Doesn’t Count
Several categories of property are excluded from the resource count entirely, no matter their value:
Your home: The house you live in and the land it sits on, regardless of market value, as long as you live there (or intend to return)
One vehicle: Your primary car or truck is excluded regardless of its value; a second vehicle is generally counted
Household goods and personal effects: Furniture, appliances, clothing, and similar items
Burial plots: One for you and one for each immediate family member
Burial funds: Up to $1,500 set aside specifically for burial expenses, if not already excluded through a burial-designated life insurance policy
Life insurance: Cash value is excluded if the combined face value of all policies on one person is $1,500 or less
If you’re navigating which of your possessions count and which don’t, the SSA’s own resource exclusions page lists the current rules in full, but the categories above cover the vast majority of situations.
ABLE Accounts: A Way To Save Without Losing SSI
An ABLE (Achieving a Better Life Experience) account lets a person who became disabled before age 26 (the age limit expands to 46 starting in 2026 under recent legislation) save money without it counting against the SSI resource limit, up to $100,000 in the account is excluded. Funds can be used tax-free for a wide range of disability-related expenses: housing, education, transportation, assistive technology, and more. For families trying to build a safety net for a disabled child or adult without jeopardizing SSI, this is one of the few legal ways to accumulate real savings.
A Plan to Achieve Self-Support (PASS)
A PASS lets you set aside income or resources toward a specific work goal, training, tuition, a vehicle to get to a job, equipment for a small business, and those set-aside funds are excluded from both the SSI income and resource calculations while the plan is active. It requires SSA approval and a written plan, but it’s a legitimate tool for someone trying to work toward independence without immediately losing benefits over savings meant for that purpose.
SSI Income Limits
To be eligible for SSI benefits, your countable income must be below the maximum federal benefit amount. For 2026, that’s $994 per month for an individual and $1,491 per month for a couple (up from $967 and $1,450 in 2025). This includes both income from work and income from other sources. If your spouse has income, some of that income may be counted. Some “in-kind” help you receive from others may also be counted.
However, some adjustments are applied to arrive at your countable income, so it may be lower than your actual income. Social Security will also reduce your countable income with certain income exclusions. For example, Social Security excludes the first $20 of unearned income and the first $65 in earned income each month. Irregular income is treated somewhat differently.
The SSA also deducts certain costs from your income. For example, if you are working and need special impairment-related work expenses, you can deduct these expenses from your income.
Other types of non-countable income include:
Food stamps
Tax refunds
Public benefits based on need
Loans that you have to repay
So, it’s worth checking your eligibility even if at first glance it seems like you have too much income or too many assets.
Sara has worked for 25 years and paid into Social Security. When she becomes disabled, she has $100,000 in an investment account and significant equity in her home.
Since Sara has accumulated sufficient work credits to be eligible for SSD and is no longer able to work due to her disability, she will likely qualify for SSD. SSD isn’t need-based, so her assets won’t be a problem. However, she will not qualify for SSI because she has significant countable assets.
Joe has worked only sporadically in the past 10 years and his ability to work is now limited by a disability. He works part-time and earns $500/month. He owns a car, has $750 in the bank and does not own a home.
Joe might still be considered disabled even while earning $500 a month, since that’s below the SGA threshold. But he may not qualify for SSD if he hasn’t earned enough recent work credits.
Because his income and assets are both under the SSI limits, he may qualify for SSI. His countable income gets subtracted from the maximum federal benefit to determine his monthly payment. In 2026, the math looks like this:
$500 in earnings minus the $65 exclusion = $435 in countable income
$994 maximum federal benefit minus $435 in countable income = $559 in monthly SSI benefits
Mary has been living off of an inheritance for more than 10 years, so has no recent work credits. Now, she is in her 50s and has become disabled. Her funds are running low–she has about $50,000 remaining. But due to her disability, she cannot return to work.
In this scenario, Mary won’t qualify for either SSD or SSI. She hasn’t accrued enough recent work credits to qualify for SSD benefits, and her $50,000 disqualifies her from SSI benefits. Since she can’t return to work, she can’t become eligible for SSD. However, when her funds run out, she may be eligible for SSI.
Disability Help Group, Call Now for a Free Case Review
Figuring out which benefits you’re entitled to and how your specific assets and income will be treated gets complicated fast. There are also legal ways to structure your finances that can affect your eligibility or your benefit amount, like ABLE accounts and PASS plans. Make sure you start your claim the right way and get everything you’re owed with our trusted team of advocates. Contact us HERE for a free consultation.
Frequently Asked Questions
Does buying a house or a car affect my SSDI benefits?
No. SSDI has no asset limit at all. You can own a home, multiple vehicles, investment accounts, or anything else, and it won’t affect your SSDI eligibility or payment amount. Only your earnings from work matter for SSDI, measured against the SGA threshold.
Can I own a house and still get SSI?
Yes. The home you live in is excluded from the SSI resource count regardless of its value, as long as you live there or intend to return to it. Selling that home and not reinvesting the proceeds into another home within the same month, though, can create a problem, since the cash from the sale becomes a countable resource.
What happens if my SSI resources go even $1 over the limit?
Going over the $2,000 (or $3,000 for a couple) limit, even briefly, can suspend your SSI payments for that month. The SSA reviews resources as of the first moment of each month, so a temporary spike, like a paycheck that hasn’t been spent down yet, can matter. If you go over the limit, contact the SSA or an advocate quickly to understand your options before it turns into an overpayment.
Do retirement accounts count against SSI?
Generally, yes. Unlike SSDI, which ignores retirement savings entirely, SSI counts most retirement accounts (401(k)s, IRAs, pensions with cash value) as resources. This is one of the most common reasons someone with modest savings still gets denied SSI.
Can I have a second car and still get SSI?
You can own a second car, but only one vehicle is excluded from your resource count. A second vehicle’s value generally counts toward your $2,000/$3,000 limit unless it falls under a separate exclusion, such as being used to get a household member to necessary medical treatment.
Does an inheritance affect my benefits?
For SSDI, no. Unearned income like an inheritance doesn’t affect eligibility. For SSI, an inheritance is counted as income in the month you receive it and as a resource in every month after that. A lump sum that pushes you over $2,000 can suspend your SSI, even if you spend most of it responsibly. Some people move inheritance funds into an ABLE account or a special needs trust to avoid losing benefits.
What’s the difference between “earned” and “unearned” income for these programs?
Earned income comes from working, wages, salary, or self-employment profit. Unearned income comes from everything else: investment income, gifts, alimony, retirement benefits, rental income you don’t actively manage. SSDI cares only about earned income (via the SGA test). SSI counts both, but applies different exclusion amounts to each.
Can my spouse’s income or assets affect my SSI eligibility?
Yes. If you’re married and living with your spouse, the SSA “deems” a portion of your spouse’s income and resources to be available to you, even if they aren’t on your claim. This can reduce or eliminate your SSI eligibility even though the program is meant to be about your individual finances. It doesn’t affect SSDI at all.
Should I talk to someone before applying if I’m not sure whether my assets disqualify me?
Yes. The rules around exclusions, deeming, and countable resources have enough exceptions that it’s easy to assume you’re ineligible when you’re not, or vice versa. A free case review can clarify which program fits your situation before you file, and how a lump sum, inheritance, or property might affect your specific claim.
How Medical Records Impact Your Social Security Disability Claim
According to the Social Security Administration (SSA), about one in four U.S. workers will become disabled before reaching retirement age. Still, most of us aren’t thinking about becoming disabled or planning for Social Security disability (SSDI) eligibility as we move through our working lives–even when medical conditions begin to develop. That can be a big mistake.
Your medical records play a critical role in the SSDI determination process. If you haven’t been receiving medical treatment for your condition or haven’t followed up with your doctors as recommended, those gaps in the record can make it more difficult for you to qualify for Social Security disability.
Why are Medical Records So Important to an SSDI Claim?
The SSA uses two different tests to determine whether you meet its definition of disabled. The first is to assess whether you meet or equal a specific disability listed in the Social Security Blue Book. The second, applied when you don’t meet or equal a listed condition, takes a wider variety of factors into account. Medical records play an important role in both processes.
Medical Records and Blue Book Listings
The Blue Book isn’t just a list of medical conditions that may qualify a person for SSDI. Instead, each listing includes very specific criteria that must be demonstrated through medical testing or other medical records. While the SSA may send an applicant for testing or medical assessment, that’s not an adequate substitute for medical records developed over time. For example:
The criteria for some listings require testing administered at certain intervals, or certain phases of the condition
The criteria for some listings requires documentation of lack of response to treatment over a period of time
The criteria for some listings requires a specific number of episodes with certain characteristics within a specific time period
Lack of sufficient medical records can mean denial. Of course, in many cases, the applicant will have the opportunity to develop those medical records and may eventually be approved on appeal. But that can mean a significant delay in receiving benefits–sometimes two years or more.
Medical Records and Grid Rules Determinations
If an applicant doesn’t meet or equal a Blue Book listing, the SSA will go on to consider the applicant’s “residual functional capacity” and whether they can work despite their medical condition or conditions.
This begins by determining the level of work the applicant is able to do in spite of their medical limitations: sedentary, light, medium or heavy. In some cases, the SSA may find that your residual functional capacity (RFC) is less than sedentary.
Medical records play an important role in this determination. For example, assessment of RFC includes a determination as to how many hours/day the applicant can sit, stand, and walk. The SSA will also consider lifting limitations. The primary source of information about those limitations is medical records showing restrictions and limitations, as well as the reason for those limits.
Once RFC has been determined, the SSA looks at other variables, such as whether you can do work you have done in the past, your level of education, the skills you have developed through past work and whether they are transferable, and even your age.
When Medical Records Aren’t Sufficient to Establish Disability
If you are applying for SSDI benefits and your medical records are patchy, you will likely have to start seeing your doctor–and possibly specialists–to establish the necessary documentation. You’ll also need to get any recommended testing. It’s also important to follow your doctor’s recommendations, such as taking medication as prescribed, going to physical therapy, or otherwise following treatment protocols.
Depending on your condition, what records you do have, how long it has been since you accrued work credits, and what additional assessment and testing are required, you may want to apply right away or wait until you have specific documentation in your record. An experienced SSDI benefits advocate can help you determine the best approach in your case. Your advocate can also tell you more about the type of documentation that would typically be required for a Social Security disability case like yours.
Additional Types of Evidence in SSDI Cases
Medical records are the bedrock of your SSDI claim, and there is no substitute for them. However, medical records alone won’t always be sufficient to establish that you are disabled. Often, day-to-day limitations are visible to you and to the people close to you, but your physician only knows about them based on your descriptions.
Here are three ways you can help the SSA understand and assess those limitations:
Make sure you keep your doctor up to date on the challenges you face in day-to-day life and any changes. Even when your doctor is just documenting what you say, it’s helpful to have that information appear consistently in medical records. That information may also inform your doctor’s diagnosis, the testing they run and their treatment recommendations.
Thoroughly and honestly complete the SSA Function Report. If there is anything in the questionnaire that you don’t understand, don’t guess. Get help to ensure that you don’t leave out something important to your claim.
Carefully choose the person who will complete the Third Party Function Report, ensuring that the person has sufficient knowledge of your day-to-day activities and challenges to provide complete, accurate information.
Medical Records are Essential for SSDI
The best time to start building a record for your SSDI claim is well before you file–even before you meet the SSA’s definition of disability. If you have a condition that worsens over time, medical records tracking the progression are very helpful. But that’s not the only reason to seek consistent medical care and testing for your condition–regular monitoring and following your doctors’ instructions are also important for management of your condition.
If you’re planning to apply for SSDI and are unsure about the adequacy of your medical records or you have received a denial due to insufficient medical documentation, we can help. Call Disability Help Group today at 800-800-3332 or fill out our contact form here.
Frequently Asked Questions
What if my medical records have gaps in treatment? Gaps in treatment don’t automatically disqualify you, but they do require explanation. If there was a valid reason (you couldn’t afford care, had no access to providers, or a doctor told you nothing more could be done), that context matters and should be documented. An advocate can help you address those gaps in a way that gives the SSA the full picture.
Can the SSA send me for their own medical exam instead of using my records? They can, and sometimes do, order a consultative examination. But that’s a one-time snapshot. It can’t substitute for records showing how your condition has progressed, how you’ve responded to treatment, or how many episodes you’ve had over time. Their exam supplements your records; it doesn’t replace them.
My doctor says I’m disabled. Isn’t that enough? Your doctor’s opinion carries weight, but the SSA makes its own determination based on specific criteria. A supportive physician is genuinely helpful, especially if they provide detailed documentation of your limitations and functional restrictions. A note that simply says “patient is disabled” won’t move the needle much on its own.
I was denied because of insufficient medical records. Can I still appeal? Yes. A denial isn’t the end of the road. The appeals process gives you the opportunity to build out your record and submit additional documentation. Many claims that are denied initially are approved at the hearing level. Getting an advocate involved at this stage can make a real difference.
It can be difficult to separate the truth from the tales that have been passed around from friends, family, social media, news stories, and advertisements.
In this article, we will debunk some of the myths that we, as advocates, tend to hear and explain what Social Security regulations really have to say about them.
Top Disability Myths and Facts
MYTH: Nobody gets approved the first time they apply for SSDI.
FACT: Many applications are indeed denied in the first round–in fact, more initial applications are denied than are approved. However, each year, hundreds of thousands of SSDI applicants are approved in the first round. The important thing to keep in mind is that getting approved for SSDI isn’t like playing the lottery. Your chances of getting approved at the initial application stage depend on a few specific variables, such as the type of claim you’re making and the strength of your application.
Working with an experienced advocate can help ensure that your application is as thorough and effective as possible.
MYTH: You can’t get Social Security disability benefits if you’re working.
FACT: This myth makes sense on the surface since SSDI is intended to provide income for workers who can no longer support themselves due to a disability. But that doesn’t mean that you can’t have any earnings at all, either when you apply for Social Security disability benefits or while you’re receiving benefits.
There are strict limits, though, so it’s important to get complete and accurate information about how earnings will impact your SSDI application and your right to continue collecting benefits.
MYTH: It’s impossible to get SSDI benefits as a young adult.
FACT: The Social Security Administration (SSA) has different expectations for younger workers than older ones when it comes to being able to adapt and retrain if they can no longer perform the type of work they’ve always done. However, a younger worker who has sufficient work credits and is unable to engage in substantial gainful activity (SGA) can absolutely qualify for SSD.
MYTH: Getting SSDI depends on whether your condition is listed in the Blue Book.
FACT: The Social Security Blue Book does contain an extensive listing of conditions that may qualify a person for benefits. But, simply having a listed condition isn’t enough–there are specific criteria that must be fulfilled for each. So, people whose conditions are listed in the Blue Book may not qualify. And others may qualify with conditions that are not listed.
The best way to find out whether or not you may be eligible for SSDI based on your medical condition is to speak with an experienced disability benefits advocate.
MYTH: If you are already getting benefits, you can get more if you put in an application.
FACT: If you are eligible for more than one benefit through Social Security (for example, retirement, survivor’s, or disability), you get whatever benefit provides the highest amount; these do not stack on each other. The only reason your benefit amount would increase is the cost-of- living increase (COLA)
MYTH: You will get $4,000 a month if you get your social security disability benefit.
FACT: The amount you receive depends on the amount you paid into Social Security over your lifetime. While the maximum someone can receive in Social Security disability benefits in 2026 is $4,152 a month, this is based on someone who contributed the taxable maximum in each year beginning at age 22 and who will start receiving benefits in 2026. Everyone’s payment amount will be different, and chances are it will not be that maximum number.
The maximum amount you can receive for SSI is capped at $994 a month.
MYTH: I cannot get early retirement from Social Security while waiting for disability.
FACT: If you are age 62 or older, you can apply for early retirement benefits while waiting for a determination of your disability. If your disability is approved, the amount you receive will be reduced for any months that you have already received your early retirement. The payment amount will then increase to the disability amount.
MYTH: There is such a thing as temporary or short term Social Security disability.
FACT: Under SSA regulations, a person must demonstrate permanent and total disability, which means they are unable to engage in substantial gainful activity due to the presence of severe impairment(s). A “severe” impairment is expected to last at least 12 months or result in death. You must also show that you are unable to return to your past relevant work and/or any other work in the national economy.
MYTH: Alcohol/drug addiction automatically qualifies a person for benefits.
FACT: This is not true. Alcohol and drug addiction do not automatically qualify a person for benefits. To receive benefits, one must have a separate disabling physical or mental condition that would remain disabling once the alcohol/drug use is stopped. In other words, the alcohol/drug use must not materially contribute to or cause the physical or mental impairment. If it does, then SSA will deny the claim. This is known as the “materiality” test.
If you know someone who is struggling with alcohol or drug use, call the SAMHSA helpline at 1-800-662-4357.
MYTH: Once I am approved, my case will never be re-reviewed by SSA
FACT: Not true. SSA can conduct a continuing disability review, known as a CDR, which is a periodic evaluation by the SSA to determine if you still qualify for benefits. According to SSA, reviews can be conducted as frequently as every 3 years if medical improvement is expected, or every 5-7 years if improvement is not expected. If SSA finds that you are no longer disabled, your benefits will stop even if you were previously granted disability.
MYTH: There are people who receive benefits immediately and they have nothing wrong with them.
FACT: Social Security takes a serious look at the medical records to determine if a person is eligible for disability benefits. While there are some conditions that do merit an immediate determination of benefits (for example, ALS or kidney disease requiring dialysis), most states are taking six to twelve months or more to make a decision. There must be support in the medical records, and many times, Social Security will send someone to their own doctor for a consultative examination. This process takes time, and a person in good health will not have the medical evidence to support getting Social Security disability benefits. Also, Social Security’s definition of disability differs from that of any other entity (including VA benefits, workers’ compensation, long-term disability, etc), so it is possible someone could receive benefits from some other source. We encourage people to concentrate on their own situation so we can make sure Social Security has the information to make a good decision on their own case.
Disability Help Group Is Here For You
If you’re navigating the Social Security disability process and feeling overwhelmed by conflicting information, you don’t have to do it alone. Our team of experienced advocates can help you separate fact from fiction, ensure your application is accurate, and give you the best chance for approval.
Call us today at 800-800-3332 or click here to schedule a free consultation and take the guesswork out of your Social Security disability claim.
Frequently Asked Questions About Social Security Disability
How much can you receive in Social Security disability benefits?
Your benefit amount depends on how much you paid into the system through payroll taxes during your working years. In 2026, the maximum SSDI payment is $4,152 per month, but most people receive less.
Can you work while applying for SSDI?
In some cases, yes. However, your monthly earnings must stay below the Substantial Gainful Activity (SGA) limit set by the Social Security Administration. Earning more than that amount can affect eligibility.
How long does it take to get a Social Security disability decision?
Most initial disability decisions take six to twelve months, though timelines vary by state and the complexity of the medical evidence.
What conditions qualify for Social Security disability?
There is no single list that guarantees approval. While the Social Security “Blue Book” lists qualifying medical conditions, applicants must also show that their condition prevents them from performing substantial work for at least 12 months.
Written and fact-checked by Donnel Beckles, COO of Disability Help Group, along with Senior Disability Advocates Jennifer Walker and Erica Chitwood.
Together, they have helped thousands of individuals nationwide navigate the Social Security Disability Insurance (SSDI) and Supplemental Security Income (SSI) application process. Their team works closely with claimants to clarify Social Security rules, review applications, and help ensure that disability claims are supported with strong medical and vocational evidence.