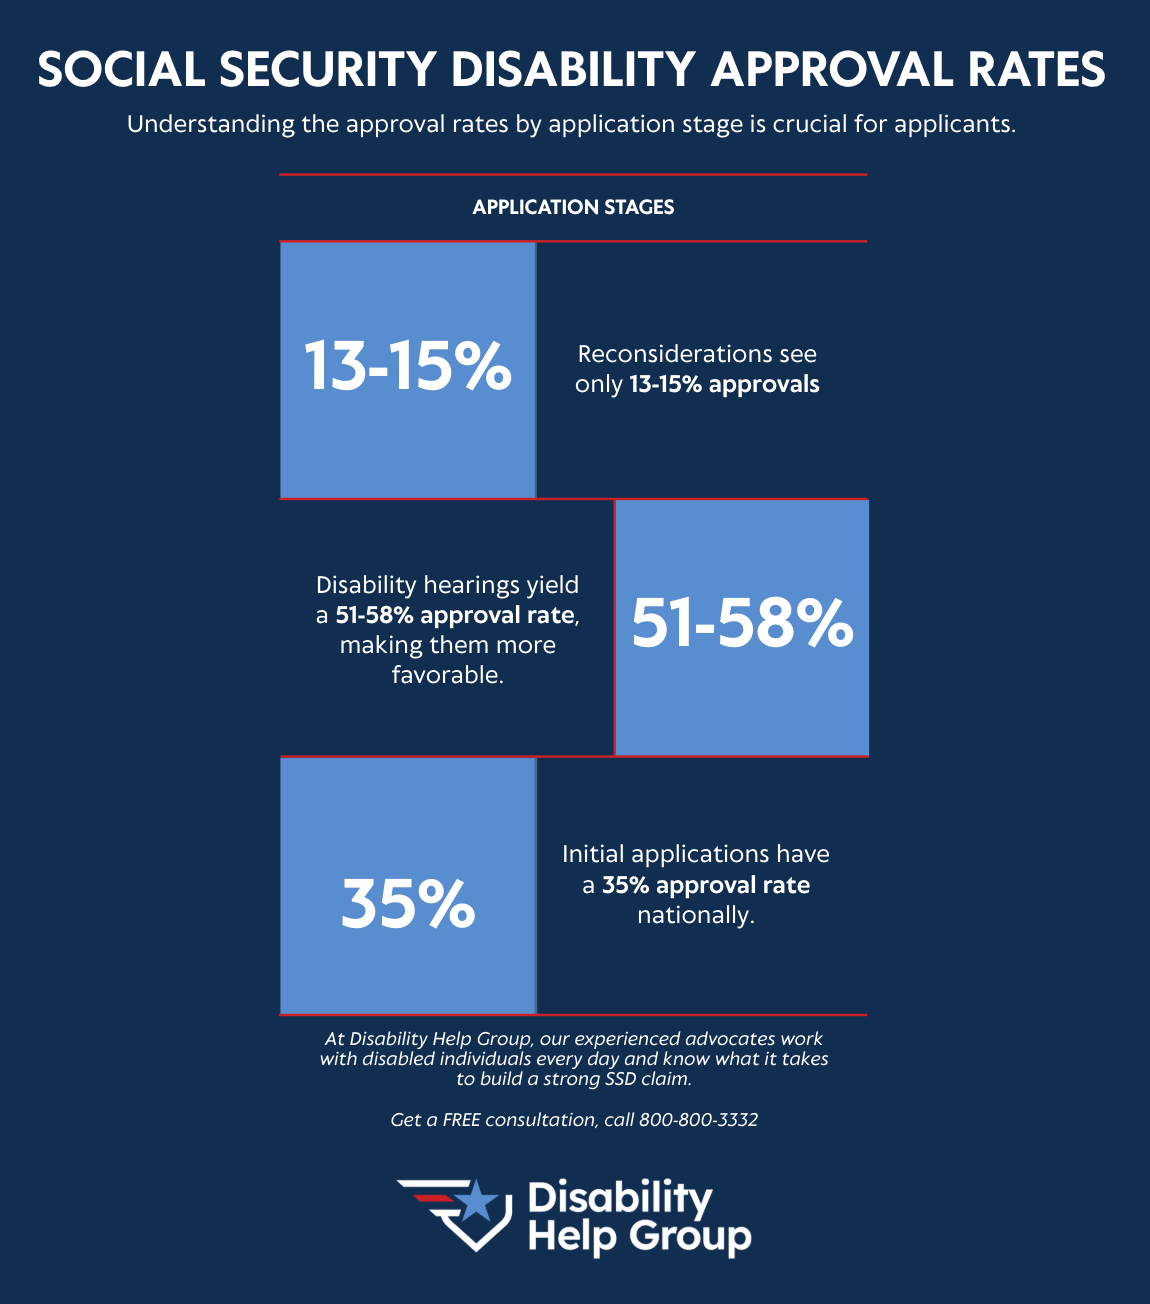
You’ve probably heard that it can be difficult to get Social Security disability benefits (SSD). Most SSD applications are denied in the first round, and it can take two years or more to get through the appeals process and secure benefits. What many people don’t know is that the chances of approval increase as you age. That’s especially true once you turn 60.
There are two ways to qualify for Social Security disability benefits. The first is to demonstrate that you meet or equal one of the medical conditions listed in the Social Security Blue Book. Simply having a listed condition isn’t sufficient to qualify for SSD. You must meet specific criteria that the Social Security Administration (SSA) sets forth to ensure that your condition is truly disabling. The specific criteria are different depending on the condition.
If you don’t meet or equal a listed condition, you may still qualify for Social Security disability benefits if the SSA determines that you are unable to engage in substantial gainful activity. That begins with a look at your past relevant work. If the SSA determines that you can still do work you have done in the past, you will not be considered disabled. If you can’t do the work you did before, the next step is for the SSA to consider whether you can do other work. This is where being aged 60 or older helps.
Where 60 Fits in Social Security’s Age Categories
Social Security sorts claimants into age brackets, and each step up makes approval easier.
A younger person is under 50. Closely approaching advanced age is 50 to 54. Advanced age is 55 and older. And within that last group, Social Security has additional rules for people closely approaching retirement age, which means 60 or older. So advanced age starts at 55, not 60. Turning 60 does not move you into advanced age. It moves you into a more favorable subcategory within it, and that subcategory comes with a specific rule that is the real reason 60 matters.
The Rule That Makes 60 a Turning Point
At Step 5, Social Security asks whether you have skills from your past work that transfer to other work you could still do. If your skills transfer, you get denied. If they don’t, the grid rules often direct a finding of disabled.
If you are 60 or older and your impairments limit you to no more than light work, Social Security can only find your skills transferable if the other work is so similar to your previous work that you would need very little, if any, vocational adjustment in terms of tools, work processes, work settings, or the industry.
Read that standard closely. It is not enough that you could learn the new job. The new job has to be nearly the same job. That is a much harder test for Social Security to meet than the one applied to someone in their fifties, and it is why representatives treat 60 as a pivotal birthday.
A similar standard applies at 55 and older when you are limited to sedentary work. The difference at 60 is that it extends up to light work, which covers far more claimants.
How the Grid Rules Work After 60
At this point, the determination hinges on grid rules. The grid looks at a combination of the applicant’s age, educational level, and past work experience to determine disability. People 60 and older are treated more favorably than any other age group in the grids. For example, an applicant in their 60s with a high school education and a skilled or semi-skilled work history that is not directly transferable to a new job would be considered disabled, while an applicant under 50 with the same combination of education and experience would not.
Where you land depends mostly on your residual functional capacity, meaning the most you can still do despite your conditions.
If you are limited to
What that generally means
Outlook at 60 or older
Sedentary work
Lifting no more than 10 pounds, sitting about six hours a day, standing or walking about two
Strong. A finding of disabled is common unless you have highly transferable skills
Light work
Lifting up to 20 pounds occasionally and 10 pounds frequently, with more standing and walking
Still favorable. The very little vocational adjustment standard applies here at 60, which is the key advantage
Medium work
Lifting up to 50 pounds occasionally and 25 pounds frequently
Difficult. The grids generally do not direct a disabled finding at medium, even for unskilled work
This is why the medical evidence still matters at 60. Age helps you enormously if you are limited to sedentary or light work. It does very little if the file says you can perform medium work. Getting your treating doctor to document your actual lifting, standing, and sitting limits is what moves you from one row of that table to another.
Only Five Years of Work History Counts Now
Social Security used to look back 15 years at your past relevant work. Under a final rule effective June 8, 2024, applied to claims pending or filed on or after June 22, 2024, the look-back period is five years. Work that started and stopped in fewer than 30 calendar days does not count at all.
This helps older claimants more than anyone. A shorter window gives Social Security fewer past jobs to say you can return to at Step 4, and fewer places to find transferable skills at Step 5. Skills from a job you left twelve years ago are now simply off the table.
If your claim was denied under the old 15 year rule and the five year rule would have changed the result, that is worth raising with a representative rather than assuming the door is closed.
The Medical-Vocational Profiles
Before Social Security even reaches the grids, it checks three special profiles. If you fit one, you are found disabled without the usual analysis, and two of them come up regularly for claimants in their 60s.
The arduous unskilled work profile, sometimes called the worn-out worker rule, applies to someone with a 35-year history of arduous unskilled physical labor, no more than a marginal education, and who can no longer do that work because of a severe impairment. Someone who spent decades in construction, farm work, or heavy manufacturing with limited schooling should ask about this.
There is also a profile for someone of advanced age with a limited education and no past relevant work at all.
These are narrow, and the criteria are strict, but they are worth checking before anything else, because they bypass the grid analysis entirely.
Check Your Date Last Insured First
This is the issue that ends more claims for people in their 60s than any medical question.
SSDI is an insurance program you pay into through payroll taxes. Coverage does not last forever after you stop working. Most people stay insured for roughly five years after they last worked, which means someone who is 63 and last worked at 56 may no longer be insured for SSDI at all.
If your date last insured has passed, you can still qualify, but you have to prove your disability began on or before that date rather than showing that you are disabled today. That is a much harder case, and it depends on medical records from years ago.
Your date last insured appears on your Social Security statement at ssa.gov/myaccount. Look it up before you do anything else. If it is approaching, filing sooner rather than later matters a great deal.
Is It Worth Applying for Social Security Disability in Your 60s?
If you are 60 or older, you may question whether it is worthwhile to apply for SSD when you are so close to being able to take early retirement benefits. The answer is yes. When you take early retirement benefits, the amount of your monthly benefit is reduced forever. However, if you qualify for SSD, you will receive your full retirement benefit amount. When you reach full retirement age, your benefits will switch to retirement benefits, but you will still receive the full monthly benefit.
A few things worth adding to that.
The switch at full retirement age happens automatically. You do not apply for it, and the amount does not change.
SSDI carries a five month waiting period from your established onset date before payments begin, and SSDI back pay can reach up to twelve months before your application date if the evidence supports an earlier onset. Early retirement pays sooner but pays less, permanently.
You can also apply for early retirement while your disability claim is pending, so you are not left with no income during the wait. If the disability claim is later approved, Social Security can pay you the difference for the months involved and adjust the permanent reduction. The mechanics depend on your onset date and filing dates, so talk this through with a representative before you file for retirement, because the sequence matters.
One thing you cannot do is collect both SSDI and retirement benefits at the same time. Social Security pays the higher of the two, not both.
What Actually Sinks Claims After 60
Age helps. It does not carry a weak file. The claims we see fail at this age usually fail for reasons that have nothing to do with the grids.
Gaps in treatment are the most common. If you stopped going to the doctor because you lost insurance when you stopped working, say so in writing. Social Security is required to consider the reason for a gap, but only if it knows about it.
Vague records are the second. A chart note saying you have arthritis does not tell an adjudicator how long you can stand. A residual functional capacity form from your treating doctor does.
Work after your onset date is the third. Earnings above Social Security’s monthly limit for substantial gainful activity can end a claim before the medical evidence is ever reviewed. The current figure is published at ssa.gov and changes each year.
Overstating your past job is the fourth, and it is counterintuitive. If you describe your old work as lighter than it really was, Social Security may find you can still do it and deny you at Step 4 without ever reaching the age rules.
Frequently Asked Questions: Disability After 60
Is it easier to get disability after 60?
Yes, if your conditions limit you to sedentary or light work. Social Security treats people 60 and older more favorably than any other age group. Age helps much less if the medical evidence says you can perform medium work.
Should I take early retirement instead of applying for disability?
Early retirement permanently reduces your monthly amount. Disability pays your full retirement benefit and converts automatically at full retirement age. You can also file for early retirement while a disability claim is pending to cover the gap, and adjust later if the claim is approved. Get advice on the sequence before you file.
Can I get disability if I stopped working years ago?
Possibly, but check your date last insured first. SSDI coverage generally lapses roughly five years after you last worked. If yours has passed, you must prove your disability began before that date, which is a harder case that relies on older medical records.
How far back does Social Security look at my work history?
Five years, as of June 2024. It used to be 15. Work that lasted fewer than 30 calendar days does not count.
What happens to my disability when I reach retirement age?
It converts to retirement benefits automatically at the same monthly amount. You do not need to reapply and your payment does not drop.
Does a high school diploma hurt my claim?
Education is one of the grid factors, and more education can make it easier for Social Security to argue you could adjust to other work. It rarely decides a claim on its own at 60, because the transferable skills standard at that age is strict regardless of education.
What is the worn-out worker rule?
It is one of the medical-vocational profiles. It can apply to someone with roughly 35 years of arduous unskilled physical labor and no more than a marginal education who can no longer do that work. If it applies, Social Security finds you disabled without going through the usual grid analysis.
Talk to a Disability Benefits Advocate Today
While the SSA makes it a little easier for older workers to qualify for SSD, success still depends on the quality of your application. Give yourself the best chance at approval by working with an experienced SSD benefits advocate from the start.
To learn more about how we can help, call (800) 800-2009 right now or contact us here now.
For most people, Social Security disability (SSD) benefits do not change when the recipient reaches full retirement age. Instead, an invisible shift takes place. When a disability recipient reaches full retirement age, the Social Security Administration (SSA) moves them from disability benefits to retirement benefits. For most people, the amount of the monthly benefit won’t change. In fact, you likely won’t notice any difference at all.
Why is My Retirement Benefit the Same as My Social Security Disability Benefit?
Social Security benefits, whether retirement benefits or SSD benefits, are based on your Social Security work history. If you have accrued sufficient Social Security work credits to qualify for SSD, your SSD benefit is the same amount as you would receive if you retired at full retirement age. Of course, that amount changes from year to year with the cost-of-living adjustment (COLA), but those increases are the same whether you are receiving retirement benefits or SSD.
Since the benefit amount for SSD and for retiring at full retirement age is identical, most people don’t see any change in their checks when they retire. However, there are a few limited circumstances in which your benefits may change.
Why Might My Social Security Benefit Change When I Reach Retirement Age?
In some limited circumstances, you will see a change in the amount of your Social Security benefit when you switch from SSD benefits to retirement benefits. The good news is that if that happens, the change is typically in your favor. This generally happens when your SSD benefits have been reduced.
One of the most common examples is a person who qualifies for both SSD and workers’ compensation disability pay. You can collect both benefits at the same time. However, the SSA has a rule that says the combined benefit cannot be more than 80% of your pre-disability earnings.
Depending on the state, workers’ compensation disability benefits typically replace 50% to 66.67% of your pre-disability earnings. For most SSD recipients, that means SSD benefits will be cut to keep the total at 80% of prior earnings. But that rule doesn’t apply to retirement benefits. So, when your SSD benefit switches to a retirement benefit, you’ll begin receiving the full amount. A similar reduction can occur with certain other types of disability benefits.
When Does SSD Switch to Social Security Retirement Benefits?
Your benefits shift from SSD to retirement benefits when you reach full retirement age. Full retirement age is different depending on the year you were born. However, under current law everyone born in 1960 or later reaches full retirement age at 67. That means that as of July of 2026, only a very small percentage of workers and Social Security disability recipients have a different full retirement date. Those born in September through December of 1959 will reach full retirement age at 66 years and 10 months of age.
It’s important to note, though, that these milestones could change. In the past several years, there have been multiple proposals to raise the Social Security retirement age.
What If I’m Also Receiving SSI?
SSI is a need-based program. Since your income from the SSA won’t change, your SSI benefit should not be affected. While different types of income are treated differently for SSI eligibility purposes and determining the amount of SSI benefits you receive, Social Security disability and Social Security retirement benefits both fall into the same category–unearned income–and so are treated the same.
What if My Spouse is Collecting Social Security on My Record?
If your spouse has been collecting Social Security benefits based on your record while you were collecting SSDI, they will continue to receive benefits after the SSA shifts you to retirement benefits. Their benefits will typically also be unchanged. However, it’s important to be aware that if they took those benefits early, their benefits will remain reduced even though you have reached full retirement age.
What Happens to Medicare When I Reach Retirement Age?
If you’re reaching full retirement age, you should already be on Medicare. SSD recipients are typically eligible for Medicare coverage after two years on disability. But anyone who has reached full retirement age and is a US citizen or permanent legal resident should already be eligible for Medicare–that kicks in at age 65. If you don’t already have Medicare coverage, you can apply. However, you will likely need to wait for the next general enrollment period (in the first quarter of the year), and may pay higher premiums because you are applying late.
Working on SSD v. Social Security Retirement
Some people who are receiving SSD work, though earnings are strictly limited. In 2026, any month in which you earn more than $1,210 counts as a trial work period–rack up just nine of those across five years and the SSA will start phasing you off of SSD.
Before full retirement age, there’s a limit of sorts on earnings for Social Security retirement benefit recipients, too. Though there’s no actual cap on earnings, anything over a set amount per year ($24,480 in 2026) triggers a reduction in benefits–you lose $1 for every $2 you earn.
That all ends at full retirement age. There’s no earnings cap and no offset. If you choose to work in retirement and you’re past full retirement age, you keep all your earnings. However, depending on the amount of your earnings, you may have to pay income tax on part of your Social Security income.
Navigating Social Security Can Be Complicated
As you can see, there are many variables impacting your Social Security disability eligibility, the amount of your benefits, and how those benefits impact or are impacted by other benefits. If you’re planning to apply for Social Security disability or have applied for SSD and been denied, an experienced disability benefits advocate can be your best resource. To learn more about what Disability Help Group can do for you, call us today at 800-800-3332 or fill out our contact form HERE for a FREE case evaluation.
FAQ’s
Does my SSD benefit amount go down when I switch to retirement benefits? No, and in some cases it goes up. SSD and full retirement age benefits are calculated from the same work history, so the amount is typically identical. The exception is if you’re also collecting workers’ comp or another disability benefit that triggered a reduction under the 80% rule, that offset doesn’t apply to retirement benefits, so your check can actually increase.
Will this affect my SSI or my spouse’s benefits? Your SSI shouldn’t change, since SSD and retirement income are both treated as unearned income for SSI purposes. If your spouse collects on your record, their benefit typically stays the same too, though if they claimed early, their reduction stays in place even after you hit full retirement age.
Do I need to do anything to make this switch happen? No. The SSA moves you from SSD to retirement benefits automatically once you hit full retirement age (67 for anyone born in 1960 or later). There’s no application or paperwork on your end.
Social Security disability (SSDI) offers an important safety net for those who are unable to continue working due to injury, illness, or a chronic medical condition. But, the SSDI program is for disabled workers. Those with no work history or insufficient work history generally won’t qualify.
However, there are two exceptions and a possible alternative. If you are unable to earn a living due to disability and don’t have the work credits required to secure SSDI benefits, it’s important to understand the narrow exceptions and what other options may be available to you. Disability Help Group, rated among the top ten disability advocacy groups nationwide, is here to help, from providing information to assisting with applications and fighting for you on your appeal.
Qualifying for SSDI
Work Credits Required for SSDI
The number of work credits required to qualify for Social Security disability depends on how old you are when you become disabled. The normal threshold for either SSDI or retirement benefits is 40 work credits. But, the Social Security Administration (SSA) recognizes that someone who becomes disabled early in adulthood won’t have had the opportunity to accrue that many credits. So, younger workers have a lower threshold.
How Are Work Credits Accumulated?
You can earn up to four Social Security work credits per year, but it’s not based on quarters worked. Instead, a certain amount of earnings (which changes from year to year) constitutes one credit. In 2026, $1,890 earns you one credit. When you reach $7,560, you’re done earning credits for the year. The good news for those with patchy work histories is that it doesn’t matter when you earned that money. If you work a single month in 2026 and earn $7,560 or more, you’ll get all four work credits for the year.
Disability Benefits with No Work Credits
Work credits are a set-in-stone technical requirement to qualify for SSDI. If you have no work credits or insufficient work credits, you cannot qualify for Social Security disability benefits. The SSA has no authority to make exceptions. However, there are two ways a disabled person without sufficient work credits may be able to get benefits from the Social Security Administration (SSA).
First, adults who became disabled before the age of 22 may be entitled to receive benefits on a parent’s record. This special type of Social Security disability is called Disabled Adult Child (DAC) benefits. However, DAC benefits are only available if the parent on whose record the adult child qualifies is receiving Social Security retirement benefits, receiving Social Security disability benefits, or deceased.
There is also an option for some disabled spouses, but the benefit available is not an SSDI benefit. Instead, it is a survivor’s benefit available to a disabled adult whose qualifying spouse is deceased.
To qualify, the surviving spouse must:
Be disabled,
Be at least 50 years old, and
Have become disabled within 7 years of the qualifying spouse’s death
There are other ways a surviving spouse may qualify for benefits, but they are unrelated to disability.
Supplemental Security Income (SSI)
Supplemental Security Income (SSI) is a completely separate program from SSDI. SSI is administered by the SSA, but is a need-based program funded by the U.S. Treasury. To be eligible, an SSI applicant must be age 65 or older, blind, or disabled and must meet income and resource requirements. The cut-off for income and assets is very low.
SSI Income Cut-off
In 2026, an individual is disqualified from receiving SSI benefits if their gross earnings from work exceed $2,073/month or their non-work income is $1,014/month or more. For a married couple, the combined limit is $3,067 in income from work and $1,511 in non-work income.
However, 21 U.S. states have higher income limits. If you live in one of the following states, you may qualify for SSI with higher income.
Arkansas
California
Delaware
Washington, DC
Georgia
Hawaii
Iowa
Kansas
Louisiana
Maryland
Michigan
Mississippi
Nevada
New Jersey
New York
Ohio
Pennsylvania
Rhode Island
South Dakota
Tennessee
Utah
Vermont
SSI Resource Limits
There is also a limit on assets. The limit is $2,000 for an individual and $3,000 for a married couple. However, there are several types of assets that are not counted when determining eligibility. The most significant of these are the home you live in and one vehicle.
How SSI Benefits are Calculated
Even if you fall below the income limits listed above, your income can significantly reduce SSI benefits. In 2026, the maximum monthly SSI benefit is $994 for an individual or $1,491 for a married couple. But that’s just the starting point. “Countable” income is deducted from the amount you will receive each month.
That calculation is complicated, as different types of income are treated differently. For example, the first $20 of most income doesn’t count. The first $65 of income earned from work doesn’t count, and only half of income from work above that amount is counted. Some other excluded income includes:
Living expenses paid by someone else
Grants and scholarships used for educational purposes
We know determining whether and what type of disability benefits you may qualify for and how to pursue them can be overwhelming. Our experienced disability benefits advocates have developed deep knowledge of eligibility requirements for SSDI, SSI, DAC, survivors’ benefits and other benefits. We also have in-depth experience with the procedures associated with:
Determining which benefits you may qualify for
Applying for SSDI benefits
Requesting reconsideration after an SSDI denial
Appealing an SSDI denial and representing clients at ALJ hearings
Applying for SSI
Managing resources for eligibility
Appealing SSI denial
Pursuing DAC or survivors’ benefits or appealing denial
No matter where you are in the process, Disability Help Group is here for you. We’ll put our extensive knowledge and experience to work to help you secure the benefits you deserve. To get started, call 800-800-3332 or contact us here.
Frequently Asked Questions (FAQ) About SSDI Without a Work History
Can I qualify for SSDI if I have no work history?
No, generally you cannot qualify for Social Security Disability Insurance (SSDI) without sufficient work credits. SSDI requires a minimum number of work credits earned through paying Social Security taxes. If you don’t have enough work credits, you may still qualify under certain exceptions like Disabled Adult Child (DAC) benefits or survivors’ benefits.
What are the work credit requirements for SSDI?
The number of work credits needed depends on your age when you become disabled. Typically, you need 40 work credits to qualify, but younger workers may require fewer. In 2026, you can earn up to four credits per year, with $1,890 of earnings equaling one credit.
How can I earn Social Security work credits?
Work credits are earned based on your annual earnings from jobs where Social Security taxes are withheld. For 2026, $1,890 earns one work credit, and once you earn $7,560, you receive all four credits for the year. Timing or gaps in work do not affect how credits are counted.
What are Disabled Adult Child (DAC) benefits?
DAC benefits allow adults disabled before age 22 to receive benefits based on a parent’s Social Security record. To qualify, the parent must be receiving Social Security retirement or disability benefits, or be deceased. This is one way to receive benefits without having your own work history.
Can a disabled spouse receive benefits without work credits?
Yes, certain disabled surviving spouses may receive benefits if they meet the following criteria:
Be disabled
Be at least 50 years old
Became disabled within 7 years of the spouse’s death
These are survivor benefits and are not classified as SSDI.
What is Supplemental Security Income (SSI)?
SSI is a need-based program for people who are blind, disabled, or age 65 and older. Unlike SSDI, SSI does not require a work history. Eligibility is based on low income and limited assets. SSI is administered by the Social Security Administration but funded by the U.S. Treasury.
What are the income and asset limits for SSI in 2026?
Income limits: $2,073/month for individuals, $3,067/month for married couples (work income), with slightly higher limits in certain states.
Resource limits: $2,000 for individuals, $3,000 for married couples. Some assets, like your primary home and one vehicle, are excluded.
How are SSI benefits calculated?
SSI benefits start with the maximum monthly amount ($994 for individuals, $1,491 for couples in 2026) and are reduced based on countable income. Certain types of income are partially or fully excluded, including scholarships, some public benefits, and living expenses covered by others.
If you’re applying for or considering applying for Social Security disability (SSD) benefits, you’ve probably heard that denial rates are high. You may also know that if you appeal, you can wait a long time for a hearing. What you may not know is that both approval rates and the wait time for an appeal hearing differ based on geography.
In other words, the chances of an initial SSD claim being approved are higher in some states than others. In fact, the rates can vary from office to office or even from Administrative Law Judge (ALJ) to ALJ within a state.
Understanding how your state compares can help you set expectations and better prepare your claim from the start.
SSD Initial Approval Rates by State (Most Recent Available Data)
Approval rates for initial SSD claims ranged from 34.8% in the lowest-approval state to 57.4% in the highest.
Just five states had initial SSD approval rates higher than 50%:
New Hampshire – 57.4% North Dakota – 56% Vermont – 54% Nebraska – 52.7% Rhode Island – 51.5%
Most states had initial SSD application approval rates between 40% and 50%. A handful fell below 40%, including:
Note: Social Security approval data is updated periodically by the SSA. Rates can change each year based on staffing, caseloads, and policy updates.
How Does Your State Stack Up?
The states with the highest and lowest approval rates for Social Security disability benefits are listed above, but what if you live in and are applying for disability benefits in one of the dozens of other U.S. states? Below are the most up-to-date approval rates per state.
It may surprise you that approval rates vary so much from state to state, given that Social Security disability is a federal program with a consistent set of requirements and eligibility criteria. There are several factors that may play a role in the SSD approval rate in a given state. It’s also worth noting that state populations vary significantly, meaning that the sample sizes are much different.
For example, in Alaska, only a few hundred claims may be decided in a quarter. In California, that number can exceed 16,000. Larger sample sizes tend to create more stable trends, while smaller states may see bigger swings.
Other factors that may affect approval rates include:
How strictly applications are reviewed locally
Staffing levels at Disability Determination Services (DDS) offices
Access to quality healthcare and medical documentation
Average age of the population
Education and work history patterns
Whether applicants receive professional help with their claim
Even small differences in documentation or wording can make or break a case.
What You Can Control to Improve Your SSD Approval Odds
While you can’t change where you live, you can take steps to strengthen your application.
Helpful tips include:
Regularly see your doctor and specialists
Follow prescribed treatment plans
Keep detailed records of symptoms and limitations
Submit complete medical evidence
Respond quickly to SSA requests
Be honest and consistent on forms
Get professional help if you’re unsure
Many denials happen simply because paperwork is incomplete or key medical evidence is missing, not because the person isn’t disabled.
The availability of quality assistance with the application process, which can make a significant difference in approval rates because an experienced advocate can ensure that the applicant avoids common mistakes and knows what type of documentation the Social Security Administration (SSA) will be looking for.
While it may be useful to know what to expect in terms of the likelihood of approval at the initial application stage in your state, it’s more important to focus on the factors that are within your control.
An experienced advocate understands exactly what the Social Security Administration looks for and can help you avoid common mistakes, strengthen medical evidence, and present your case clearly.
At Disability Help Group, our team works with disabled individuals across the country every day to file new applications, requests for reconsideration, and appeals. We know how to build claims that give you the best possible chance of approval.
To learn more about how we can help, call 800-800-3332 or request your free case evaluation through our contact form HERE.
Frequently Asked Questions (FAQ)
What state has the highest SSD approval rate?
Historically, smaller states like New Hampshire, North Dakota, and Vermont often report higher initial approval rates. However, rates change yearly.
What state has the lowest SSD approval rate?
Some larger or high-volume states tend to have lower approval percentages, often due to heavy caseloads. Arizona and several southern states have historically reported lower rates.
Does moving to another state improve my chances?
No. Moving solely for approval odds usually isn’t practical and won’t guarantee success. Strong medical evidence matters far more than geography.
How long does SSD approval take?
Initial decisions typically take 3–6 months. Appeals and hearings can take longer depending on backlog and location.
Are SSD appeals more successful than initial claims?
Yes. Many applicants are approved during reconsideration or at a hearing with an Administrative Law Judge.
Should I get help with my SSD application?
Yes. Professional assistance can significantly reduce mistakes, strengthen your evidence, and improve your overall chances of approval.
Poor Sleep Quality May Make Alzheimer’s Disease Conditions Worse
Alzheimer’s disease is a cognitive disability that gradually reduces a patient’s ability to remember and process information. The condition can cause many symptoms, including inability to sleep and disturbances in normal sleep patterns. Researchers are now looking at these sleep disturbances as a clue to how Alzheimer’s damages the cognitive function of those afflicted with the disease.
A new study published in the Journal of Alzheimer’s Disease has found that chemical changes in the brain can be caused by the sleep disturbances commonly associated with Alzheimer’s. Researchers at the University of California-Irvine studied how common Alzheimer’s sleep patterns, which include being awake for 40 percent or more of normal sleep hours and sleeping during the day, may affect memory problems.
Studies have also suggested that sleep patterns earlier in life may contribute to later dementia risk. Both insufficient sleep and sleeping longer than average have been linked to a greater likelihood of developing dementia. However, it has been hard to determine whether these sleep changes contribute to the disease or simply reflect early symptoms.
The research simulated jet-lag style sleep disturbances by altering the normal light and dark times with a shortened dark period, causing the Alzheimer’s-inflicted mice used in the study to have disturbed sleeping patterns. The mice with disturbed sleeping patterns showed significant learning impairments compared to the mice with normal circadian rhythm cycles.
Further research has found that the sleep disturbances led to a decrease in glutathione levels in brain cells. Glutathione is an antioxidant that assists in the prevention of damage to essential cellular components in the brain. A deficiency in this antioxidant can cause redox changes in brain cells, which can affect brain metabolism and inflammation. These conditions are related to the progression of Alzheimer’s, and if medications could target and prevent redox reactions, it could lead to new treatment options.
Does Alzheimer’s qualify for Social Security Disability benefits?
Alzheimer’s disease is just one of many cognitive disorders that can qualify a person for Social Security disability benefits. If you or a loved one can no longer work and earn a living due to a mental disorder or cognitive decline, the Disability Help Group is here to assist with your case. Contact us online or call us at 1-(800)-800-3332 to schedule a consultation with our disability advocates!
The short answer to this question is “maybe.” The Social Security Administration (SSA) does recognize depression as a possible cause of disability.
Millions of Americans suffer from depression, with symptoms including (but not limited to):
Suicidal ideation
Poor concentration
Decreased energy
Loss of interest in activities
Memory problems
Sleep changes
Irritability/agitation
Not everyone who has been diagnosed with depression is eligible for Social Security disability benefits (SSD).
How Does the SSA Determine SSD Eligibility for Depression?
Depression falls under the Listing of Impairments in the Social Security Blue Book. The Blue Book lists specific criteria for each condition. To qualify for disability based on the listing, an SSD applicant must fulfill the requirements in paragraph A below AND the requirements in EITHER paragraph B or paragraph C:
Suffer from at least five of a longer list of depression symptoms, which include:
Depressed mood
Diminished interest in nearly all activities
Appetite disturbance with weight change
Sleep disturbance
Psychomotor agitation or retardation
Decreased energy
Feelings of guilt or worthlessness
Difficulting concentrating or thinking
Thoughts of death or suicide
Show extreme limitation of one or marked limitation of two of the following:
Ability to understand, remember, and apply information
Ability to interact with others
Ability to concentrate, persist, or maintain pace
Ability to adapt or to manage oneself
Show all of the following:
A medically documented history of the condition existing for at least two years
Ongoing medical care, therapy, and/or a structured environment that reduces symptoms
Minimal capacity to adapt to changes in environment
What If You Don’t Meet The Blue Book Criteria?
If you don’t meet the Listing requirements above, don’t give up. People who don’t meet a Listing can still qualify for SSD if they can so that they are medically unable to engage in substantial gainful activity (SGA). This is a more complex assessment in which the SSA looks at what types of work you have done in the past, your educational level, and your age to determine whether you are capable of earning a living despite your disability.
Get Help with Your Social Security Disability Claim
Demonstrating that you are disabled by a mental health condition can be more difficult than securing benefits for some physical disabilities. That’s because an X-ray or more sophisticated scan will show exactly how deteriorated your spine is, but there’s no objective test to prove that you’ve lost energy or are feeling anxious.
Whether you’re just applying for SSD for depression or you have been denied and want to appeal, your best next step is to talk to an experienced disability benefits advocate. At Disability Help Group, our advocates know the type of documentation required to establish a claim and how best to prove the severity of your disabling condition. To learn more about how we can help, call us at (800) 800-3332, or contact us here.